


Understanding What is Home Buyers Plan: Your 2026 GTA Guide
Let's face it: staring at property prices in the GTA can feel intimidating. Saving up for that down payment is often the biggest hurdle for aspiring homeowners. But what if you could get a major head start using money you’ve already saved? That's exactly where the Canadian Home Buyers' Plan (HBP) comes in.
This powerful government program allows you to withdraw up to $60,000 from your Registered Retirement Savings Plans (RRSPs)—completely tax-free—and put it directly toward your down payment. Think of it as a smart, interest-free loan you give to yourself.
Your Key to Homeownership in the GTA
For so many people dreaming of buying a home in competitive markets like Brampton or Mississauga, the down payment is the one thing standing in the way. The Home Buyers' Plan is designed to help you clear that barrier sooner.
It gives you access to a significant pool of your own money, letting you jump into the property market with more confidence and buying power. This isn't just a financial tool; for thousands of Canadians, it’s the key that unlocks the door to their first home.
What Is The Home Buyers' Plan In Simple Terms?
Imagine your RRSP is a savings chest you’re building for retirement. The HBP gives you a special key to open that chest early, but only for one specific purpose: buying your first home.
The best part? You get to take that money out without paying a single dollar in income tax on the withdrawal. Normally, pulling money from an RRSP before retirement triggers a hefty tax bill. The HBP lets you sidestep that completely, as long as you follow the rules.
The core idea is simple: You are borrowing from yourself. The money was always yours, but the HBP provides the framework to use it for a home purchase now and pay it back to your retirement fund over 15 years.
The Home Buyers' Plan At A Glance
Getting a firm grasp of the rules is the first step. Here are the essential details of the HBP for a quick overview.
| Feature | Details for 2026 |
|---|---|
| What It Is | A program letting you borrow from your RRSPs for a down payment. |
| Maximum Withdrawal | $60,000 per person. |
| Tax Status | The withdrawal is tax-free. |
| Repayment Period | You have 15 years to repay the amount to your RRSP. |
| Who Qualifies | Primarily for first-time home buyers in Canada. |
This structure gives you a clear and manageable way to seriously boost your down payment. For a couple buying their first home together, this means you could potentially access up to $120,000 from your combined RRSPs.
In this guide, we'll walk you through exactly how to make this powerful program work for you, providing a clear path toward owning your first home right here in the GTA.
How the Home Buyers Plan Actually Works
So, what exactly is the Home Buyers' Plan? The best way to think about it is like getting a short-term, interest-free loan from your "future self" to help your "present self" buy a home. You’re tapping into your own retirement savings (your RRSP), but in a structured, government-approved way that avoids the usual tax hit.
This isn’t free money from the government; it’s a powerful tool that lets you access your own funds when you need them most—for your down payment. The Home Buyers' Plan (HBP) has been a game-changer for first-time home buyers across the GTA since 1992, giving them a much-needed boost to enter the market.
Under the plan, you can withdraw up to $60,000 tax-free from your RRSPs to buy or build a home. The catch? You have to repay it back into your RRSP over a 15-year period. You can find all the official details on the Government of Canada website, but here’s what you really need to know.
The $60,000 Withdrawal Limit Explained
The big number to remember is $60,000. That's the maximum amount one person can pull from their RRSPs under the HBP.
Now, here’s where it gets really powerful. If you’re buying a home with a partner or spouse who also qualifies as a first-time buyer, you can each withdraw $60,000. That gives you a combined total of $120,000 to put toward your down payment. In a market like the GTA, that kind of cash can make a world of difference.
One crucial rule to watch out for: any money you plan to withdraw must have been sitting in your RRSP account for at least 90 days. This is to prevent people from making a last-minute contribution just to pull it right back out. Good planning is key.
What Is a First-Time Home Buyer?
The term “first-time home buyer” can be a little confusing because the government’s definition is more flexible than most people think.
You’re generally considered a first-time home buyer if, in the last four years, you did not live in a home that you or your current spouse or common-law partner owned. This is often called the "four-year rule."
This means even if you owned a home in the past, you might still qualify for the HBP today. It’s also a big help for people re-entering the market after a separation or divorce, giving them a fresh start without being penalized. Sorting out your mortgage pre-approval early on will help clarify exactly where you stand.
What Counts as a Qualifying Home?
The HBP is designed to help you buy the home you’re actually going to live in. A "qualifying home" is simply a housing unit in Canada that you intend to use as your principal residence within one year of buying or building it.
This covers almost every type of home you’ll find across the GTA, including:
- Detached or semi-detached houses in family-friendly Brampton and Caledon neighbourhoods.
- Townhouses and row houses that are so popular in Mississauga.
- Condominium units in the heart of Toronto or its surrounding urban centres.
The most important part is your intent to live there. You can’t use the HBP to buy a rental property or a weekend cottage. It’s all about securing your primary home.
Of course. Here is the rewritten section, crafted to sound like an experienced human expert and match the provided examples.
Checking Your Eligibility for the HBP
So, you’ve heard about the Home Buyers' Plan and how it can give your down payment a serious boost. But the big question is, can you actually use it? The good news is that figuring out your eligibility doesn’t have to feel like digging through complicated government forms.
Let’s break it down. The HBP is built around three core requirements you generally need to meet:
- You must be considered a first-time home buyer.
- You need a written agreement to buy or build a home in Canada.
- You must intend to occupy the home as your main residence within one year of owning it.
These might sound straightforward, but the details are what really count. Let's unpack each one so you know exactly where you stand.
Are You a First-Time Home Buyer?
This is where most people get tripped up, but the definition is more forgiving than you might think. Generally, you’re considered a first-time home buyer if you have not lived in a home owned by you or your current spouse/partner in the last four years.
This "four-year rule" is a huge advantage for many. It means that even if you owned a property years ago, you might be able to use the HBP again to get back into the market.
To make it even clearer, we've put together a simple checklist to help you quickly assess your situation.
HBP Eligibility Self-Assessment Checklist
Use this simple checklist to see if you meet the primary conditions for using the Home Buyers' Plan.
| Eligibility Question | Yes / No | What This Means for You |
|---|---|---|
| Are you a Canadian resident? | You must be a resident of Canada when you withdraw the funds and when you buy or build the home. | |
| Do you have a signed agreement to buy or build a home? | A firm Agreement of Purchase and Sale is required to start the withdrawal process. | |
| Is this your first time buying a home? (Or have you not owned a home you lived in for the past 4 years?) | This is the core "first-time buyer" rule. Past ownership doesn't automatically disqualify you if enough time has passed. | |
| Do you intend to live in this home as your principal residence within one year of purchase? | The HBP is for your primary home, not an investment property. | |
| Are the funds you want to withdraw currently in an RRSP? | Only funds held in a Registered Retirement Savings Plan can be used for the HBP. | |
| Have the funds been in your RRSP for at least 90 days? | This is a strict rule. Funds deposited less than 90 days before withdrawal are not eligible. |
This checklist gives you a great starting point. If you answered "Yes" to these questions, you're likely on the right track! If you have any "No" answers, don't worry—there might be exceptions that apply to you.
Special Conditions for HBP Eligibility
Life isn’t always simple, and the HBP has special rules for certain situations. These exceptions are crucial, as they can open the door to the plan even if you don't fit the typical first-time buyer mold.
A key takeaway: The HBP rules are designed with real-life situations in mind. A significant life change, like a relationship breakdown, doesn't automatically disqualify you from accessing this powerful tool for your next chapter.
For example, if you're going through a separation or divorce, you might be able to use the HBP even if you don't meet the four-year rule. As long as you’ve lived apart from your ex-spouse for at least 90 days and are buying a new place (or buying out their share of your previous home), you can often qualify.
The plan also has provisions if you’re buying or building a more accessible home for a relative with a disability. In this case, you can use the HBP to help them, even if you’re not a first-time home buyer yourself.
The Critical 90-Day RRSP Rule
Now for a rule you absolutely cannot overlook: any money you plan to withdraw under the HBP must have been sitting in your RRSP account for at least 90 days.
The government put this rule in place to stop people from dropping a large sum into their RRSP, getting a quick tax deduction, and then immediately pulling it out for a down payment. They want to see a genuine commitment to saving.
This means you need to think ahead. If you’re planning to use the HBP, make sure your contributions are in your account well before you need the cash. A last-minute deposit won't be eligible, and that could throw a major wrench in your down payment plans right when you're ready to make an offer.
The 15-Year Journey to Paying Yourself Back
The word 'repayment' can sound a little scary, but let's reframe how we think about the Home Buyers' Plan. This isn't a loan you owe to a bank; it's a promise you're making to your future self—to put back the retirement savings you borrowed. You're simply paying yourself back.
The whole process is designed to be manageable. Let's walk through the 15-year timeline so you can see how you can comfortably rebuild your RRSP while enjoying your new home.
When Do the Repayments Begin?
One of the best parts of the HBP is the built-in breathing room. You don’t have to start making payments the day you get your keys. The repayment clock doesn't actually start until the second year after the year you took the money out.
So, if you withdraw your HBP funds anytime in 2026, your first repayment isn't due until 2028. The Canada Revenue Agency (CRA) will send you a Notice of Assessment after you file your 2027 taxes, which will clearly lay out your HBP balance and the minimum payment needed for 2028.
How Your Annual Repayment is Calculated
The math here is refreshingly simple. The CRA just takes the total amount you withdrew and divides it by 15. That’s your minimum annual payment.
Your minimum annual repayment is simply 1/15th of the total amount you borrowed from your RRSP. You can always choose to repay more each year, but you can't repay less without a tax consequence.
Let’s see how this plays out in a real-world scenario.
Repayment Example: A Brampton Buyer
Imagine you're a first-time homebuyer in Brampton and you pulled $45,000 from your RRSP to help with your down payment. Here’s what your repayment plan would look like:
- Total HBP Withdrawal: $45,000
- Repayment Period: 15 years
- Minimum Annual Repayment: $45,000 ÷ 15 = $3,000
This means you’d need to contribute at least $3,000 back into your RRSP each year for the next 15 years to stay on schedule. You can play with these numbers yourself to see how they fit into your budget by using our handy mortgage calculator to plan your finances.
What Happens If You Miss a Payment?
Life happens, and sometimes making the full payment might be tough. If you miss a payment or can't repay the full minimum amount, the consequence is straightforward: whatever you didn't repay gets added to your taxable income for that year.
Using our Brampton buyer example, let's say your required payment was $3,000, but you only managed to contribute $1,000 to your RRSP. The remaining $2,000 would be added to your income on your tax return, and you'd pay income tax on it. You haven't defaulted on a loan, but you do lose the tax-free growth on that portion for that year.
It's encouraging to know that most people stay on track. In a recent year, HBP repayments averaged 92% on-time in high-income GTA pockets like Oakville, well above the national average. You can explore more real estate trends and data on the CREA media hub.
Tips for a Smooth Repayment Journey
Staying on top of your HBP repayments is simple with a little planning. Here are a few practical tips to make it effortless:
- Set It and Forget It: Set up automatic monthly or bi-weekly transfers from your chequing account to your RRSP. A simple $250 transfer each month will easily cover a $3,000 annual repayment.
- Use Your Tax Refund: Many of my clients find it effective to use their annual tax refund to make their HBP payment in one go.
- Pay It Down Faster: If you're able to, making extra payments will reduce your outstanding balance and shorten your repayment schedule. This gets your RRSP back to full strength and growing for your retirement even sooner.
A Step-by-Step Guide to Using the HBP in the GTA
Knowing about the Home Buyers' Plan is one thing, but actually putting it to work in the fast-paced Greater Toronto Area market is a whole different ball game. Think of this as your practical playbook for using the HBP, guiding you from the first bit of planning all the way to having the funds ready for your down payment.
We’ll walk through the process chronologically, with a special focus on navigating the offer and closing timelines common in hotspots like Brampton and Mississauga. The process itself isn't difficult, but timing and attention to detail are everything. Let's break down the exact steps you’ll take to turn your RRSP savings into a down payment on your first home.
Step 1: Confirm Your Contributions and Eligibility
Before you even dream of scrolling through listings, your first move is a quick financial health check. Log into your RRSP accounts and look for two crucial details: your total available balance and how long your contributions have been in the account.
Remember the 90-day rule we talked about? Any money you want to pull out using the HBP must have been sitting in your RRSP for at least 90 days. A last-minute deposit made just before you put in an offer won't count, which is why planning ahead is so important. This is also the perfect time to give the first-time home buyer criteria a final check to make sure you tick all the boxes.
Step 2: Get Your Paperwork in Order
Once you have a signed Agreement of Purchase and Sale for a home in the GTA, it’s go-time. To get your hands on the funds, you'll need to fill out Form T1036, Home Buyers' Plan (HBP) Request to Withdraw Funds from an RRSP.
This form is your official request to your financial institution. You’ll complete "Area 1," which asks for your personal info and details about the home you're buying. Your RRSP issuer—your bank or investment firm—will handle the rest in "Area 2."
A few pro tips for this stage:
- One Form Per Account: If your RRSP savings are spread across different banks or investment firms, you need to submit a separate T1036 form to each one.
- Act Fast: In the GTA, closing dates can be tight—often just 30-60 days. Get your forms in right after your offer is accepted to prevent any delays.
- Keep Your Team in the Loop: Let your real estate agent and mortgage broker know you’re using the HBP. They are crucial for making sure all your timelines line up perfectly.
Step 3: Coordinate the Withdrawal with Your Bank
After you submit Form T1036, your financial institution will get to work processing the request. The funds are usually released within 5 to 10 business days, but it’s always a smart idea to confirm the exact timeline with your bank.
The money lands in your chequing or savings account with no tax withheld—that’s the real magic of the HBP. From there, you simply transfer it to your lawyer's trust account before your closing day, where it will be applied to your down payment.
For Harman Sangha's clients at RE/MAX Gold, this strategy has been a game-changer. Over 200 Brampton first-timers he’s worked with have used the HBP, withdrawing an average of $42,000. That covered a massive 25% of their down payments. You can dive deeper into housing market data to see how trends are creating new opportunities for buyers across the region.
This simple flow chart shows the three-part journey of your HBP funds, from withdrawal to repayment.
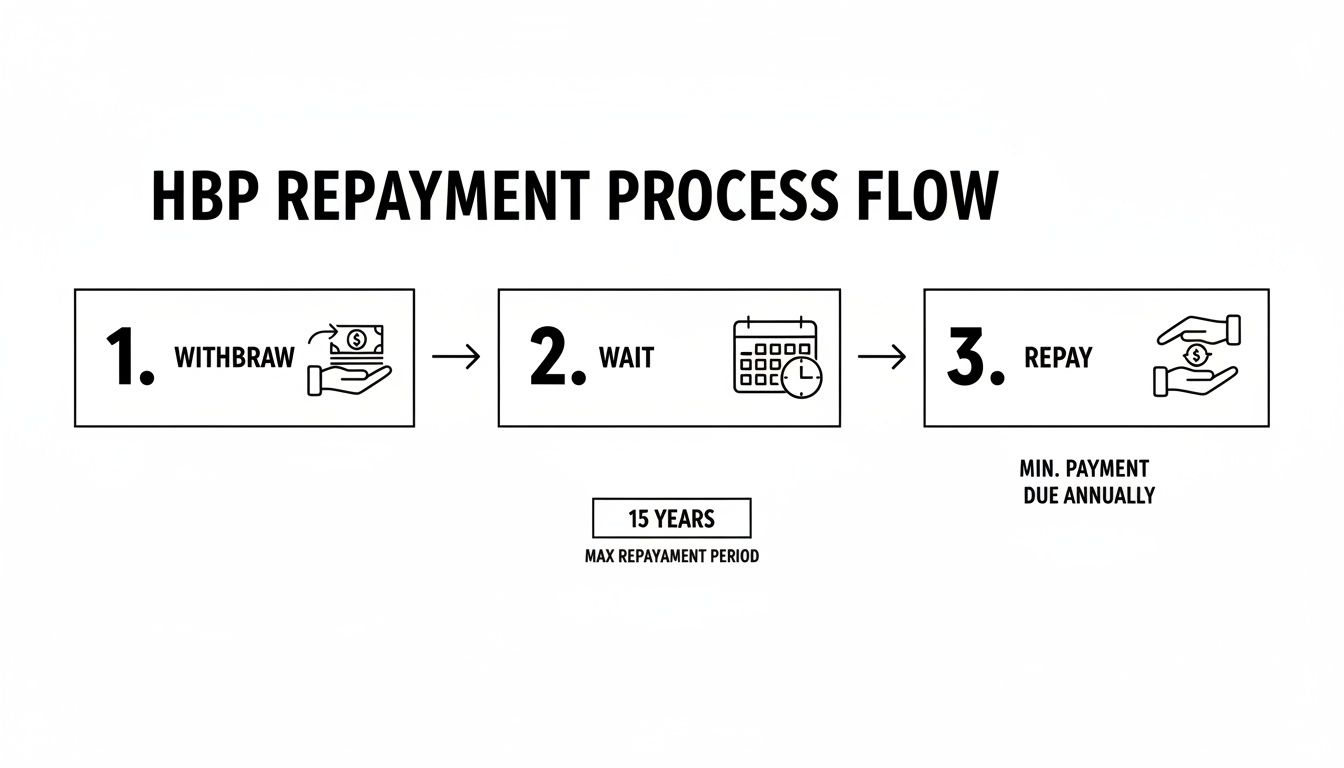
The visual makes it clear: you withdraw the money, get a long grace period, and then start paying it back slowly.
Case Study: A Couple Buys in Mississauga
Let’s watch this play out in a real-world scenario. Meet Maya and Liam, a couple excited to buy their first place. They’ve been diligently contributing to their RRSPs for years.
Their Goal: Buy a semi-detached home in Mississauga for around $950,000. Their Advantage: Both qualify as first-time home buyers. Maya has $70,000 in her RRSP, and Liam has $65,000.
They find the perfect home, and their offer is accepted. Here’s exactly how they used the HBP:
- Combined Power: They decide to each withdraw the new maximum HBP amount of $60,000.
- Paperwork: They each fill out a T1036 form and immediately submit it to their respective banks.
- Funding: Within two weeks, a grand total of $120,000 is deposited into their joint chequing account, completely tax-free.
- Down Payment: This $120,000 becomes the core of their down payment, helping them secure a much better mortgage rate and avoid the highest CMHC insurance premiums.
For Maya and Liam, the HBP was the key that unlocked the door to homeownership, turning their long-held dream into a reality.
Stacking the HBP with Other Buyer Programs
Understanding the Home Buyers' Plan is a great starting point. But the real power of the HBP is unlocked when you learn how to combine it with other government programs. By "stacking" these incentives, you can dramatically increase your down payment and supercharge your purchasing power.
Think of it like building with LEGO blocks. The HBP is a big, solid foundation. On its own, it’s helpful. But when you start adding other pieces—like the First Home Savings Account (FHSA) and tax rebates—you can build something much bigger and more impressive than you ever could with one block alone.
The Ultimate Duo: HBP and the FHSA
The First Home Savings Account (FHSA) is hands-down the most powerful partner to the Home Buyers' Plan. This newer account was designed specifically for first-time buyers, blending the best features of an RRSP and a TFSA into one incredible tool.
Here’s how it gives you a triple advantage:
- Tax-Deductible Contributions: Just like an RRSP, any money you put into an FHSA can be deducted from your taxable income, which means a lower tax bill for you.
- Tax-Free Growth: Once inside the account, your investments and savings grow completely tax-free.
- Tax-Free Withdrawals: When you’re ready to buy your first home, you can withdraw the full amount—your original contributions plus all the growth—entirely tax-free.
This is a game-changer. You can contribute up to $8,000 per year to an FHSA, up to a lifetime maximum of $40,000. Now, let's look at what happens when you pair this with the HBP.
By using both the HBP and the FHSA, a single buyer can access up to $100,000 for a down payment—that’s $60,000 from their RRSP and $40,000 from their FHSA. For a couple buying together, that number doubles to a staggering $200,000.
In a competitive market like the GTA, this kind of financial boost can be the difference between buying a condo and securing a semi-detached home, or between paying hefty mortgage insurance and making a full 20% down payment.
Down Payment Power: Combining HBP and FHSA
This table clearly shows just how much more powerful your down payment becomes when you stack these two programs.
| Program Combination | Individual Buyer Potential | Couple Buying Together Potential |
|---|---|---|
| HBP Only | $60,000 | $120,000 |
| FHSA Only | $40,000 | $80,000 |
| HBP + FHSA Stacked | $100,000 | $200,000 |
As you can see, combining these programs more than doubles the potential of using just one, giving you a massive advantage when it's time to make an offer.
Don't Forget the Land Transfer Tax Rebate
On top of boosting your initial down payment, you can also get a significant chunk of cash back in your pocket right after you close on your new home. In Ontario, first-time home buyers are eligible for a substantial rebate on the Land Transfer Tax (LTT).
And this isn't just a small discount. The provincial rebate can be worth up to $4,000. If you're buying a home in Toronto, you get to double-dip and claim an additional municipal LTT rebate of up to $4,475. That adds up to nearly $8,500 that goes right back into your bank account—perfect for covering closing costs, legal fees, or new furniture.
By combining the upfront power of the HBP and FHSA with the post-closing relief of the LTT rebate, you create a comprehensive financial strategy that puts you in the strongest possible position. To explore even more ways to make your homeownership dream a reality, check out our extensive guide on government programs for home buyers. It's all about using every tool available to your advantage.
Common Questions About the Home Buyers’ Plan
When you're navigating the GTA real estate market, theory is one thing, but real-world scenarios are what truly matter. This section tackles the specific "what if" questions that pop up for buyers in places like Mississauga and Brampton. Let's get you the clear, practical answers you need.
Can I Use the HBP for a Pre-Construction Condo?
Absolutely. The Home Buyers' Plan is a fantastic tool for pre-construction properties, which is a huge advantage in the GTA where so many new developments are being built.
The key is timing. You can make your HBP withdrawal as long as you have a signed agreement to purchase with the builder. The main rule is that you must intend to make this condo your principal residence within one year of acquiring it—which means one year from the final closing date when you officially take ownership.
What if My Partner Is Not a First-Time Home Buyer?
This is a very common situation, and the answer is straightforward. If you qualify as a first-time home buyer but your spouse or common-law partner does not, you can still use the HBP.
You would be able to withdraw up to $60,000 from your own RRSP. Your partner, however, would not be able to make an HBP withdrawal from their RRSP. It’s an individual qualification, so one person's status doesn't prevent the other from participating.
Can My Spouse and I Both Use the HBP for the Same Home?
Yes, and this is where the HBP becomes incredibly powerful for couples. If both you and your spouse or partner qualify as first-time home buyers, you can each withdraw up to $60,000 from your respective RRSPs.
This allows you to pool your resources for a combined total of up to $120,000. This substantial amount can dramatically boost your down payment, helping you secure a better mortgage rate and potentially avoid CMHC insurance costs.
What if I Sell My Home Before Fully Repaying the HBP?
Life changes, and it’s not uncommon to sell your home before the 15-year repayment period is over. Don't worry—selling your home does not automatically trigger a demand for the full HBP balance to be repaid immediately.
Your repayment schedule simply continues as normal. You are still required to make your minimum annual 1/15th repayment to your RRSP each year until the balance is paid off. The obligation is to your RRSP, not the property itself, so you just continue the payment plan as you were before.
Navigating these specific scenarios is where having an experienced guide makes all the difference. For personalized advice on how the Home Buyers' Plan can fit into your unique situation, connect with the team at Harman Sangha Realtor : Re/max Gold by visiting https://www.harman.homes.